What If the Foundation Surviving Forever Isn’t the Point?
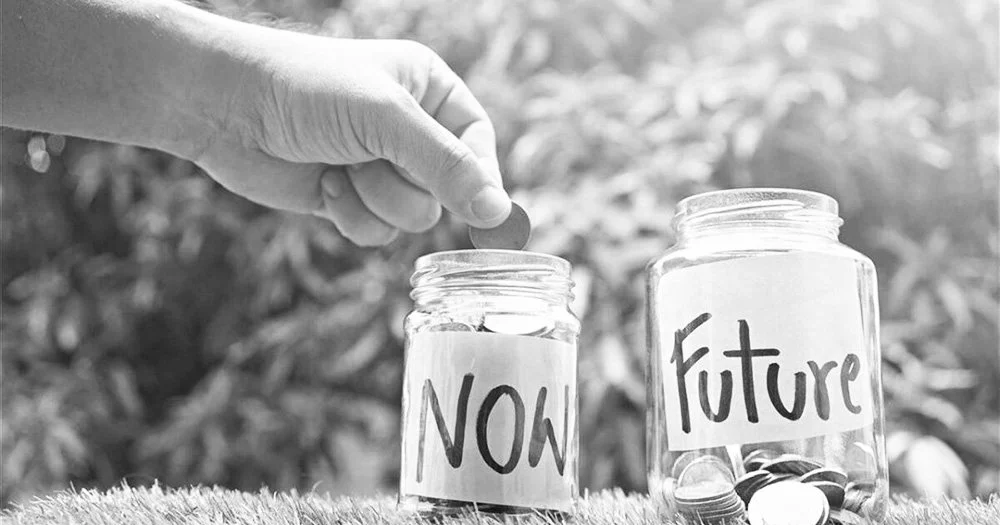
If we want to help the future, we have to help now.
By Lindsay Jordan
This morning, AJ, my illustrious sales and marketing manager sent me an article from Philanthropy Roundtable titled, “Flawed Math Makes Bad Policy: Higher Payout Mandates Would Shortchange Future Generations.”
My immediate, highly academic response was: Oh, hell no.
The article is a response to recent criticism of private foundation payout rates and proposals that would require foundations to distribute more of their assets to charitable causes. And to be fair, Philanthropy Roundtable makes some legitimate technical points about how foundation payout is calculated.
Fine. Let’s give them those.
Because the math isn’t actually what bothers me. The premise does.
The entire argument rests on an assumption that philanthropy has repeated so often that we barely notice it anymore: Preserving philanthropic wealth is itself a philanthropic good.
And I would like to challenge that assumption. Aggressively.
First, 5% Doesn't Necessarily Mean 5% Goes to Nonprofits
Let's get something out of the way. When most people hear that private foundations have a 5% payout requirement, they reasonably assume that means foundations must give approximately 5% of their assets to charity every year.
Not quite.
The IRS allows a variety of expenditures to count as qualifying distributions, including certain administrative expenses, direct charitable activities, program-related investments, charitable-use assets, and qualifying set-asides.
So the familiar shorthand, "Foundations have to give away 5%, "isn't really accurate.
It's closer to: Foundations must make qualifying distributions based on a statutory formula roughly equivalent to 5% of applicable investment assets.
Not quite as catchy, is it? And there is an even more important distinction here. Five percent is a legal requirement. That does not make it a moral ideal. It does not make it an economic optimum.
And it certainly doesn't mean Congress descended from Mount Sinai carrying stone tablets that said: Thou shalt distribute five percent, and no one shall ever question this again.
Congress created the rule. Congress has changed the rule before. We are allowed to ask whether the rule still accomplishes what we want it to accomplish.
Because people made rules.
The Question Isn't Whether the Math Works
The Roundtable spends considerable time explaining why critics can calculate foundation payout incorrectly. Fair enough. But this is where we start answering an accounting question instead of the public-policy question.
The question isn't simply: Are foundations complying with current payout law?
The much more interesting question is: What did the public buy?
When someone places assets into a private foundation, we don't treat that transaction exactly like putting money into a brokerage account. We provide favorable tax treatment because the money has been dedicated to charitable purposes.
That is a bargain.
Private wealth receives public subsidy in exchange for anticipated public benefit. So asking how quickly those resources should produce public benefit isn't an attack on philanthropy.
It is literally the public-policy question. And compliance with the existing law cannot be offered as proof that the existing law is good.
"We followed the rules" and "these are the right rules" are two completely different arguments.
Then the Article Gives the Game Away
Here's the sentence that stopped me:
“Preserving and growing foundation assets generates far more charitable support over decades than spending those assets quickly.”
And there it is. Not math. Philosophy.
The argument assumes that our objective should be maximizing the number of charitable dollars available over an indefinite period of time. But why?
Why isn't the objective maximizing public benefit?
Why isn't it reducing suffering?
Why isn't it strengthening communities?
Why isn't it solving enough of the underlying problem that someday we need less philanthropy?
Imagine discovering an extraordinarily effective treatment for childhood cancer and saying: "We could fund treatment now, of course. But if we invest this money for another 30 years, imagine how many treatments we'll be able to afford then."
Technically true. Also completely effing bananas. Money sitting in an investment account has the capacity to create impact. It is not, itself, impact.
Congratulations, Your Billion Dollars Became Two Billion Dollars
The Roundtable offers a hypothetical example:
A foundation begins with $1 billion. Its assets grow to $2 billion. A 5% payout that once produced approximately $50 million can now produce approximately $100 million.
See? More money for charity! And yes. That's mathematically correct.
But there's another number in that example: $1.9 billion.
That's roughly what remains under private philanthropic control after the hypothetical $100 million payout. We're invited to celebrate the larger stream without ever questioning the necessity of maintaining - and preferably enlarging - the reservoir.
Meanwhile, nonprofit organizations are being told:
Be sustainable.
Diversify your revenue.
Build reserves.
Reduce overhead.
Collaborate.
Innovate.
Measure everything.
Prove your impact.
Find more donors.
Do more with less.
This creates one of the strangest contradictions in modern philanthropy: We have made the holder of the money sustainable while asking the doer of the work to compete for the payout.
Then we call the arrangement "stewardship."
About Those "Future Generations"
The headline warns that requiring foundations to distribute more money would "shortchange future generations." This phrase is doing Olympic-level rhetorical work. Who exactly are these future generations? Apparently, they are future nonprofit grant recipients.
But today's children are a future generation.
Today's students are a future generation.
Today's housing crisis will shape a future generation.
Today's climate decisions will affect a future generation.
Today's weakened civic institutions will be inherited by a future generation.
Today's underfunded communities will become tomorrow's underfunded communities unless somebody interrupts the cycle.
Money invested in an endowment isn't the only investment capable of compounding. People compound, too. Communities, education, health, economic opportunity, social infrastructure - all compound.
Preventing a problem today can be substantially cheaper - and substantially more humane - than allowing it to grow for another 30 years while the money intended to address it enjoys excellent market returns.
So no, spending philanthropic resources today does not inherently steal from future generations. Sometimes it is exactly how we invest in them.
And Then There's Donor Intent
The Roundtable also defends both spend-down and perpetual foundations as legitimate expressions of donor intent. I have no objection to donors having intentions. I have lots of intentions.
But once society subsidizes the transfer of private wealth into a charitable vehicle, donor preference cannot be the only interest in the room. The public has an interest, too.
Which means we're allowed to ask an uncomfortable question: How long should one person's intentions control tax-advantaged charitable wealth? Twenty years? Forty? One hundred? Two hundred? Forever?
Interestingly, Congress wrestled with this very question when it created the modern private-foundation regulatory framework in 1969. Lawmakers considered limiting the lifespan of private foundations before ultimately adopting payout requirements instead.
Perpetuity isn't a law of nature. It's a policy choice. And policy choices can be revisited.
Five Percent: Minimum or Mission?
Perhaps the most fascinating part of this entire debate is what has happened psychologically around the payout requirement. The legal requirement is supposed to function as a floor. Yet research on very large foundations consistently finds payout clustering remarkably close to that floor.
That should make us curious. If social need increases dramatically, why doesn't philanthropic payout increase dramatically? If nonprofit organizations experience enormous demand, why doesn't more capital move? If a once-in-a-generation crisis occurs, why do we suddenly discover that foundations can give significantly more?
COVID taught us something extremely important about philanthropy. When foundations perceive an emergency, money can move faster. Applications can get shorter. Reporting requirements can disappear. Restrictions can loosen. General operating support can happen. Payout can increase. The machinery suddenly becomes remarkably flexible.
Which leaves us with another uncomfortable question: Who gets to decide what constitutes an emergency?
A pandemic? Absolutely.
Homelessness? Maybe.
Childhood poverty? Let's discuss it at the next board meeting.
Climate change? Please submit an LOI.
Systemic racial wealth inequality? Our application cycle reopens in March.
Who Exactly Is the "Responsible Steward"?
The Roundtable argues that foundations need time to identify fiscally and operationally strong nonprofits and determine which opportunities will most effectively advance their missions.
This is another idea philanthropy has repeated so often that we've stopped hearing what it says. The people holding the money are the stewards. The people doing the work are the applicants.
A nonprofit organization might have spent 30 years housing families, treating patients, protecting children, restoring ecosystems, educating students, defending civil rights, feeding people, caring for animals, or strengthening neighborhoods.
But before we trust them with $75,000, somebody managing a billion-dollar endowment needs to examine their audited financial statements, logic model, theory of change, evaluation plan, sustainability strategy, board participation, demographic data, operating budget, project budget, and 14 attachments.
Just to make sure they're responsible. The assumption underneath traditional philanthropy remains remarkably durable: Money knows better than proximity. I call bullshit.
What If the Foundation Isn't the Thing We're Supposed to Preserve?
This is the question I keep coming back to. What is philanthropy actually for?
If philanthropy exists to preserve philanthropic institutions, our current system makes perfect sense.
Protect the endowment.
Maintain purchasing power.
Grow the assets.
Distribute enough to demonstrate public benefit.
Repeat forever.
But if philanthropy exists to move privately accumulated resources toward public benefit, then accumulation cannot automatically be counted as success.
A billion-dollar endowment is not a billion dollars of impact. It is a billion dollars of potential impact.
The impact happens when the money does something. A child eats. A family gets housed. A student graduates. A patient receives treatment. A wetland is protected. A survivor gets somewhere safe. A community gains opportunity. A problem gets smaller.
And maybe - this is the truly radical part - if philanthropy succeeds spectacularly, the foundation gets smaller, too.
So Let's Talk About the Math. But Let's Talk About the Bargain, Too.
I'm perfectly happy to have a technically accurate conversation about payout formulas. Let's calculate net investment assets correctly. Let's understand carryovers. Let's distinguish qualifying distributions from grants. Let's model different payout rates over different market conditions. Let's debate the consequences.
Good policy requires good math. But math cannot answer the question underneath all of this: What do we believe charitable wealth is for?
If its purpose is primarily to preserve itself so that charitable institutions can exist forever, then higher payout requirements certainly threaten that model.
But if charitable capital exists to produce public benefit, then preservation is only valuable insofar as it advances that purpose.
Future generations deserve resources. But they also deserve functioning communities, healthy people, strong institutions, economic opportunity, a livable planet, and fewer problems handed down to them because we decided preserving the money intended to address those problems was itself the highest form of stewardship.
So perhaps the question isn't: Can foundations survive a higher payout rate?
Perhaps the question is: Why did we decide foundations surviving forever was the goal?
Because the thing we're supposed to preserve for future generations isn't the foundation. It's the future generation.